

Blogs
24vdc And 48vdc Electronic Fuse Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-17
24vdc And 48vdc Electronic Fuse Market
Overview
The 24vdc And 48vdc Electronic Fuse Market encompasses the manufacturing and distribution of electronic protection devices designed to safeguard electrical circuits operating at these voltage levels. These electronic fuses serve as critical components in power management systems, offering precise overcurrent protection to prevent damage to sensitive electronics and ensure operational reliability. Their core functionalities include rapid response to electrical faults, reducing downtime, and enhancing system safety, which are vital for modern industries such as telecommunications, renewable energy, and industrial automation.
Supporting the evolving needs of advanced technological applications, the 24vdc And 48vdc Electronic Fuse Market plays a fundamental role in maintaining system integrity. This market's significance is underscored by its contribution to the stability and efficiency of power distribution, especially in decentralized and renewable energy setups. As electronic systems become more compact and complex, the demand for reliable, compact, and intelligent fuse solutions grows, making this market a key enabler of technological advancement.
Market Size and Growth
The current market value for the 24vdc And 48vdc Electronic Fuse Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 3.5 billion, reflecting a compound annual growth rate (CAGR) of about 11%. Growth is driven by increasing adoption of renewable energy systems, expanding industrial automation, and the rising need for efficient power protection solutions in IoT devices and electric vehicles.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2919
Key Drivers
• Rising deployment of renewable energy and microgrids
• Increasing automation in industrial sectors
• Growing adoption of electric vehicles and EV charging stations
• Advancement in electronic fuse technology
• Expansion of IoT and smart device integration
Restraints
• High costs of advanced electronic fuse components
• Technical challenges in miniaturization and integration
• Stringent regulatory standards and certification requirements
• Limited awareness in emerging markets
• Compatibility issues with legacy systems
Segmentation
• By Type: Resettable fuses, Non-resettable fuses
• By Deployment: Indoor, Outdoor
• By Enterprise Size: Small, Medium, Large
• By End User: Industrial, Commercial, Residential, Automotive, Telecommunications
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, demand is driven by industrial automation and renewable energy projects, with a focus on safety and reliability standards. Europe shows strong growth due to its aggressive renewable targets and smart grid initiatives. The Asia-Pacific region is experiencing rapid adoption fueled by expanding manufacturing, urbanization, and electric vehicle markets. Latin America is gradually increasing its infrastructure investments, while the Middle East & Africa are exploring opportunities within oil, gas, and emerging renewable projects.
Opportunities
• Expansion in EV and charging infrastructure markets
• Integration with smart grid and energy storage systems
• Development of miniaturized, high-performance fuse solutions
• Adoption in industrial IoT and automation platforms
• Growth prospects in emerging economies
Key Companies
ABB Ltd., Eaton Corporation, Littelfuse Inc., Schneider Electric, Siemens AG, TE Connectivity, Murata Manufacturing Co., Ltd., Bel Fuse Inc., Honeywell International Inc., Phoenix Contact, Amphenol Corporation, and ABB.
Conclusion
The overall outlook for the 24vdc And 48vdc Electronic Fuse Market remains positive, with long-term growth driven by technological innovation and expanding energy and automation sectors. As industries increasingly prioritize safety, efficiency, and system resilience, the strategic importance of electronic fuses will continue to grow. The market’s potential for sustained expansion makes it a vital component of modern electrical infrastructure, with the 24vdc And 48vdc Electronic Fuse Market poised for significant development in the coming years.
Related Reports
Compact Electro Hydraulic Actuator Market , Size Share and Analysis | Report 2033
Industrial Pneumatic Actuator Market , Size Share and Analysis | Report 2033
High Force Linear Actuator Market , Size Share and Analysis | Report 2033
Industrial Electric Linear Actuator Market , Size Share and Analysis | Report 2033
Solder Smoke Absorber Market , Size Share and Analysis | Report 2033
Industrial Fume Eliminator Market , Size Share and Analysis | Report 2033
Industrial Vacuum Dust Extractor Market , Size Share and Analysis | Report 2033
Air Separation Module Market , Size Share and Analysis | Report 2033
Hot Shift Power Take Off Market , Size Share and Analysis | Report 2033
Hydraulic Power Take Off Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
PW Consulting: Pipe Flanges Market Hits $5.34B in 2025, Projects $7.03B by 2032 at 4.01% CAGR
By PW Consulting, 2026-09-17
Navigating the 2026 Industrial Landscape: Why the Pipe Flanges Market Demands Strategic Foresight
In the complex ecosystem of industrial infrastructure, few components hold as much critical importance as the humble pipe flange. Serving as the vital connective tissue in piping systems, flanges ensure safety, pressure integrity, and modularity across sectors ranging from energy extraction to municipal water management. Yet, as we move deeper into 2026, the market for these essential components is undergoing a subtle but profound transformation. Static supply chains are giving way to dynamic networks influenced by regulatory shifts, raw material volatility, and regional industrial pivots. For executives, procurement leaders, and investors, understanding the trajectory of the worldwide pipe flanges market is no longer optional; it is a strategic imperative.
Worldwide Pipe Flanges Market
Our latest market research, spanning historical data from 2020 through the forecast period extending to 2032, offers a comprehensive lens into this evolution. This report is not merely a collection of statistics; it is a decision-support tool designed to help organizations navigate uncertainty. By analyzing revenue trends, competitive maneuvers, and regulatory frameworks, we provide the intelligence necessary to secure supply lines, optimize capital expenditure, and identify high-growth opportunities in a market projected to expand significantly over the coming years.
The Macro Trajectory: Growth Amidst Volatility
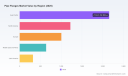
The global pipe flanges market has demonstrated resilience in the face of recent economic headwinds. Based on our analysis, the market revenue stood at approximately 5,342 million USD in the base year of 2025. Looking forward, the forecast period from 2026 to 2032 suggests a steady upward trajectory, with the market expected to reach over 7,000 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.01 percent.
While these top-line figures provide a snapshot of health, the true value lies in understanding the drivers behind the numbers. The period from 2020 to 2025 revealed patterns of recovery and adjustment, with revenue figures fluctuating as industries adapted to post-pandemic operational realities and shifting energy demands. The transition from 2025 into 2026 marks a critical inflection point. The modest growth observed in the immediate year suggests a market stabilizing after previous adjustments, setting the stage for more robust expansion in the latter half of the decade. For stakeholders, this implies that while immediate spikes may be tempered, the long-term fundamentals remain strong, driven by ongoing industrialization and infrastructure renewal projects globally.
Structural Dynamics: Segmentation and Demand Drivers
To truly leverage this market intelligence, one must look beyond aggregate revenue and understand the structural composition of demand. The market is differentiated by several key dimensions, including material composition, product type, end-user industry, and geographic region. Each of these segments presents distinct risk profiles and opportunity sets.
Material and Manufacturing Considerations
The choice of material remains a primary determinant of value within the supply chain. Carbon steel continues to hold a dominant position due to its cost-effectiveness and widespread application in standard industrial piping. However, the demand for stainless steel and alloy steel flanges is gaining momentum, driven by sectors requiring higher corrosion resistance and pressure tolerance. This shift is not merely technical; it is economic. Recent fluctuations in raw material costs have placed pressure on manufacturing margins. For instance, recent data indicates that U.S. Producer Price Index values for stainless steel have hovered significantly above historical baselines, reflecting ongoing cost volatility. Simultaneously, global steel prices in the U.S. market have shown stabilization in the low-to-mid 800s per short ton following previous fluctuations. These input cost dynamics directly influence the pricing strategies and production planning of manufacturers specializing in carbon and alloy steel flanges.
Application End-User Trends
Demand is heavily concentrated in specific industrial verticals. The oil and gas sector remains a cornerstone of consumption, leveraging flanges for upstream, midstream, and downstream infrastructure. Closely following are the petrochemical and chemical industries, which require high-integrity fittings for complex processing networks. Power generation also represents a substantial portion of the market, as utilities upgrade aging grids and explore new energy frameworks. Water and waste management sectors contribute a steady stream of demand, often driven by municipal infrastructure investments. Each of these end-users faces unique regulatory and operational pressures that dictate their procurement cycles and specification requirements.
Regional Perspectives
Geographically, the market is distributed across major economic zones. Asia Pacific represents a significant volume of activity, reflecting rapid industrialization and massive infrastructure projects in the region. North America and Europe maintain strong market positions, supported by mature industrial bases and ongoing maintenance replacements. Emerging regions in Latin America and the Middle East and Africa also contribute to the global total, often linked to energy exploration and development projects. Understanding the regional balance is crucial for companies looking to optimize their logistics networks or target specific export markets.
Regulatory Shifts Reshaping Compliance and Specifications
One of the most critical developments for market participants in 2026 is the regulatory landscape. Standards governing pipe flanges are not static; they evolve to address safety concerns and technological advancements. A major milestone occurred with the release of the ASME B16.5-2025 standard for Pipe Flanges and Flanged Fittings. This update, which covers nominal pipe sizes from 1/2 through 24, introduces revised pressure-temperature ratings based on updated ceiling values.
For manufacturers and engineers, compliance with the ASME B16.5-2025 edition is paramount. The standard introduces new definitions for key operational terms and adds additional ASTM materials for consideration. Furthermore, it includes a new appendix addressing minimum temperature limits and revises variables that impact design calculations. Pipe flanges must now comply with updated requirements for materials, dimensions, tolerances, marking, and testing to ensure pressure integrity in industrial piping systems. These changes ripple through the supply chain, affecting inventory planning, certification processes, and product development. Companies that fail to align their offerings with these updated specifications risk disqualification from bids or, worse, liability issues in the field. Our report details how these regulatory shifts are influencing manufacturer strategies and procurement timelines.
Competitive Landscape: Consolidations and Capabilities
The market structure is characterized by a mix of specialized manufacturers and large diversified conglomerates. Our analysis indicates a moderate level of market concentration, with the top three companies holding a combined share of approximately 16.4 percent and the top five holding around 22.85 percent. This fragmentation suggests that while there are key leaders, there is still ample room for niche players and regional specialists to thrive.
Several key companies define the current competitive arena. In the United States, Texas Flange and Federal Flange, both headquartered in Houston, remain prominent. Texas Flange specializes in ANSI, API, and AWWA pipe flanges in carbon steel, stainless steel, and alloys, catering to petrochemical, process, and waterworks industries with both standard and custom solutions. Federal Flange distinguishes itself as a leading manufacturer of ANSI and API 6A pipe flanges and fittings, with a strong emphasis on fast-turnaround capabilities and large diameter solutions. Similarly, Federal Flange and Allied International Group, with operations spanning Houston and Italy, operate as global producers and distributors of fittings, flanges, pipes, and PVF products through multiple manufacturing divisions.
On the technology and precision front, Swagelok Company supplies precision pipe flanges and fluid system components for critical applications, while Nippon Steel Corporation leverages advanced forging technology to offer precision pipe flanges for global industrial use. European and Asian players also exert significant influence. Metalfar S.p.A. in Italy and Flanschenwerk Bebitz GmbH in Germany produce high-performance steel pipe flanges and fittings for international markets. In China, Longan Flange manufactures a comprehensive range of steel flanges, including weld neck, blind, and orifice types, while Hebei Shengtian Pipe-Fitting Group Co., Ltd. stands as a major manufacturer of carbon steel pipe fittings and flanges.
Recent activity highlights the proactive nature of these competitors. In April 2026, Allied International Group participated as a major player in fittings, flanges, and pipes at TUBE Düsseldorf 2026. Similarly, Arrow Pipes participated as a Platinum partner at the same trade fair, the leading event for the tube and pipe industry. These engagements underscore the importance of face-to-face networking and product demonstration in a market where specifications and quality assurances are paramount. Additionally, the release of the ASME standard in May 2025 saw industry-wide responses, with companies adjusting their catalogs and compliance documentation to meet the new criteria.
Strategic Implications for 2026 Decision Makers
For business leaders, the insights contained in this report translate into actionable strategic directives. First, supply chain resilience must be prioritized. Given the fluctuations in raw material costs and the geographic dispersion of manufacturing hubs, relying on single-source suppliers exposes organizations to significant risk. Diversifying sourcing strategies across regions with different cost structures and regulatory environments can mitigate these vulnerabilities.
Second, compliance agility is a competitive advantage. With the ASME B16.5-2025 standard now in effect, companies that can rapidly certify their products and communicate compliance to customers will capture market share from slower-moving competitors. This requires investment in quality assurance teams and updated testing protocols.
Third, innovation in custom solutions offers higher margin opportunities. As seen with companies like Texas Flange and Federal Flange, the ability to provide custom-engineered connectors and large diameter capabilities allows manufacturers to serve specialized projects that standard off-the-shelf products cannot address. Understanding the specific needs of end-users in oil and gas or power generation can reveal gaps in the current market offerings.
Conclusion: Access the Full Intelligence
The worldwide pipe flanges market is at a junction where historical stability meets future complexity. The projection of growth to over 7,000 million USD by 2032 offers promise, but realizing value in this environment requires more than passive observation. It demands a granular understanding of material costs, regulatory updates, regional demand shifts, and competitive maneuvers.
This article has only scratched the surface of the available intelligence. To fully equip your organization for the decisions ahead, we invite you to access the complete Worldwide Pipe Flanges Market research report. Inside, you will find detailed segmentation analysis, comprehensive company profiles, deep dives into regulatory impacts, and scenario-based forecasting that goes beyond the high-level trends discussed here. Do not navigate the 2026 industrial landscape with incomplete data. Secure the full report today and turn market insight into strategic advantage.
Stainless Steel Flanges Market
For detailed analysis of this topic, please visit the official page: Worldwide Pipe Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global PCB Epoxy Resin Market to Reach $4.9 Billion by 2032, Growing at 5.88% CAGR
By PW Consulting, 2026-09-17
Strategic Imperatives in the Worldwide Epoxy Resin for PCB Market: Navigating Growth, Volatility, and Trade Friction Through 2032
The printed circuit board (PCB) industry is currently navigating a transformation defined by the simultaneous pull of three powerful forces: the insatiable demand for high-performance electronics, the tightening grip of global trade defenses, and the relentless pressure of raw material cost volatility. Epoxy resin remains the cornerstone material for modern PCBs, dictating everything from thermal stability and dielectric performance to environmental compliance and manufacturing yield. For executives, procurement leaders, and investors, understanding the trajectory of this essential material is not merely an exercise in supply chain management; it is a prerequisite for securing competitive advantage in sectors ranging from consumer electronics to aerospace and defense.
In this context, PW Consulting has released a comprehensive new market study focused on the Worldwide Epoxy Resin for PCB Market. This strategic intelligence report provides the depth and rigor required to make informed decisions through the end of the decade and beyond. By integrating historical performance data with forward-looking scenario modeling, the study offers a clear roadmap for navigating one of the most technically demanding and geopolitically sensitive segments of the electronic materials supply chain.
Market Trajectory and the Case for Long-Term Planning
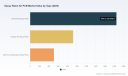
The scale of the global epoxy resin market for PCBs underscores its critical role in the broader electronics ecosystem. Recent historical data and baseline projections reveal a market that has consistently expanded, driven by the proliferation of advanced computing, automotive electrification, and the relentless miniaturization of electronic components. From a base exceeding $3,280 million in 2025, the market is projected to follow a robust upward trajectory, reaching a total revenue value of nearly $4,900 million by 2032. This expansion reflects a compound annual growth rate of approximately 5.88 percent over the forecast period, signaling a market that is growing steadily rather than experiencing erratic, cyclical swings.
However, the headline figures only tell part of the story. For strategic planners, the more telling narrative lies in the divergence between growth rates in mature regions versus high-velocity markets, and in the shifting balance of demand across application verticals. The interplay between volume expansion and value dynamics becomes particularly pronounced when analyzing how specific end-use sectors, such as communications and networking or automotive electronics, are modulating their material requirements in response to technological roadmaps and regulatory pressures.
The Technical Divergence Driving Demand Shifts
Demand for epoxy resin in PCBs is no longer uniform. As electronic devices push the boundaries of speed, density, and reliability, the material specifications required by PCB manufacturers are fragmenting into highly specialized formulations. The market is increasingly bifurcating between standard grades that serve high-volume, cost-sensitive applications and premium grades engineered for extreme performance. This bifurcation is most visible in the tension between brominated epoxy resins, which have long dominated due to their cost-effectiveness and flame retardancy, and halogen-free alternatives, which are gaining traction as environmental regulations and corporate sustainability mandates tighten globally.
Simultaneously, the push toward high-frequency, high-speed signal integrity in 5G infrastructure, advanced server base stations, and high-layer packaging substrates is accelerating the adoption of high-Tg (glass transition temperature) and specialized epoxy systems. These formulations, while typically commanding higher unit economics, are becoming indispensable for applications where thermal management, dimensional stability, and low dielectric loss are non-negotiable. The competitive dynamics within this landscape are heavily influenced by players who have vertically integrated their capabilities, from raw monomer production to finished copper-clad laminates and PCB inks.
Competitive Landscape: Vertically Integrated Giants and Regional Power Players
The competitive architecture of the global epoxy resin for PCB market is shaped by a mix of established multinational chemical corporations, regional specialists, and aggressively expanding Asian manufacturers. Market concentration remains a defining characteristic, with the top five firms accounting for a significant share of global revenue and the top three wielding a commanding portion of the market. This concentration amplifies the strategic importance of understanding not just who the players are, but how their distinct technological portfolios, geographic footprints, and capital allocation decisions are reshaping the supply-demand equilibrium.
Technology Moats and Regional Specialization
Japanese and Korean chemical giants continue to anchor the high-performance end of the spectrum. Companies such as DIC Corporation, Mitsubishi Gas Chemical Company, and Resonac Corporation have built formidable reputations around low-dielectric-loss formulations, high thermal resistance, and advanced novolac and BT resin systems tailored for multilayer PCBs, IC package substrates, and high-layer printed wiring boards. Their focus on materials for server, base station, and high-frequency applications positions them at the forefront of the technology curve, where performance premiums justify higher price points.
Epoxy Resins for Casting and Lamination Market
In tandem, Taiwanese and mainland Chinese manufacturers are executing aggressive capacity expansion strategies designed to capture volume growth and climb the value chain. Nan Ya Plastics Corporation, a vertically integrated producer of bisphenol-A based liquid and solid epoxy resins, exemplifies this approach, supplying high-Tg FR-4 materials and electronic-grade formulations with excellent electrical, mechanical, and dimensional stability for multilayer PCBs. Meanwhile, Chinese players such as Hongchang Electronics and Shengyi Technology are scaling up production of electronic-grade functional resins, halogen-free compositions, and high-Tg liquid systems, often with explicit targets in copper-clad laminates and high-end electronic materials.
Recent Strategic Shifts and Competitive Realignments
The competitive landscape has been further reshaped by a series of high-impact developments over the past year. In mid-2025, Zhuhai Hongchang commenced production on its Phase II project, adding 140,000 tons of annual capacity for liquid epoxy resin and reducing unit costs by an estimated 15 percent, thereby strengthening its cost competitiveness in the electronics and electrical sectors. By the end of 2025, the company disclosed an action plan for a Phase III project targeting an additional 80,000 tons per year of electronic-grade functional epoxy resin, alongside a high-end copper-clad laminate project, signaling a clear intent to deepen its footprint in advanced electronic materials.
Geopolitical and trade dynamics have introduced an equally potent layer of complexity. In May 2025, the U.S. International Trade Commission issued a final affirmative determination of material injury to the domestic industry from subsidized and dumped imports of epoxy resins from South Korea, Taiwan, and Thailand, effectively clearing the path for antidumping and countervailing duties. This ruling, which noted negligible imports from China and India, has immediate implications for cross-border supply chain configurations and pricing strategies. Across the Atlantic, the European Union imposed definitive anti-dumping duties on epoxy resin imports from China, South Korea, Taiwan, and Thailand in July 2025, while India followed suit in November 2025 with a five-year anti-dumping duty regime on liquid epoxy resin imports from a broad set of exporting nations.
On the commercial front, cost pressures are reverberating through the value chain. In April 2026, Mitsubishi Gas Chemical announced a 30 percent across-the-board price increase for products within its electronic materials division, including copper-clad laminates and related epoxy-based substrates, citing rising costs for copper foil, electronic cloth, and special epoxy resins. This move underscores the challenge manufacturers face in balancing input cost inflation with margin preservation, and highlights the growing importance of raw material forecasting in procurement planning.
Supply Chain Volatility and the Raw Material Matrix
No strategic assessment of the epoxy resin for PCB market is complete without a granular examination of the raw material environment. Bisphenol A, the key feedstock for most epoxy resin production, has exhibited notable price volatility, with downward pressure emerging in North America during the final quarter of 2025 as Asian offers intensified and downstream demand softened across polycarbonate and epoxy applications. Concurrently, epoxy resin prices across Asia followed a weak to bearish trend in the second half of 2025, characterized by ample supply, elevated inventories, and limited cost support from stable pricing in both bisphenol A and epichlorohydrin.
This macroeconomic backdrop creates a complex environment for procurement and production planning. On one hand, fading raw material costs can provide temporary relief and improve margin potential for resin producers and PCB fabricators. On the other hand, the protective trade measures enacted by the United States, the European Union, and India are artificially constraining supply flows in certain corridors, potentially decoupling regional price dynamics and creating arbitrage opportunities or, conversely, supply bottlenecks. Companies that fail to model these dual forces, commodity price cycles and trade policy interventions, risk suboptimal inventory positioning and unanticipated cost exposures.
Report Architecture: The Operational Intelligence Inside the Study
The Worldwide Epoxy Resin for PCB Market study is engineered to serve as a decision-making toolkit rather than a static data summary. The full report delivers a multi-layered analysis that bridges macroeconomic trends, granular segmentation, competitive profiling, and actionable supply chain intelligence. Key components of the study include:
- A detailed historical and forecast revenue analysis spanning the base year through the end of the forecast window, allowing readers to benchmark current performance against long-term trajectories and identify inflection points in the growth cycle.
- Segment-level breakdowns that dissect market size and growth dynamics across resin types, including brominated, halogen-free, and high-Tg specialized formulations, alongside application-driven analysis spanning consumer electronics, automotive electronics, communications and networking, industrial and medical equipment, and aerospace and defense sectors.
- A comprehensive regional assessment that quantifies the relative weight of key geographies and explores the structural drivers, including manufacturing footprints, end-user demand profiles, and regulatory environments, shaping market performance in each territory.
- Deep-dive company profiles covering the leading global and regional players, with a focus on their technological capabilities, product portfolios, strategic positioning, and recent operational or financial developments that influence competitive dynamics.
- An integrated regulatory and trade analysis that maps the impact of antidumping and countervailing duty proceedings, environmental compliance mandates, and raw material feedstock trends, providing a holistic view of the forces that will shape pricing, sourcing, and market access over the forecast horizon.
- Scenario-based strategic implications designed to help stakeholders stress-test their planning assumptions against plausible shifts in demand, input costs, trade policy, and technological adoption rates.
By consolidating these dimensions into a single, rigorously sourced reference, the report enables executives to move beyond reactive management and toward proactive, evidence-based strategy formulation. Whether the objective is to evaluate capacity investment timing, optimize global sourcing architectures, benchmark against incumbent competitors, or assess the viability of entry into high-growth application segments, the study provides the granularity required to reduce uncertainty and accelerate decision velocity.
Why This Study Matters for 2026 Decision-Making
The decisions made in 2026 will set the tone for the entire forecast period. As the industry absorbs the effects of newly imposed trade remedies, responds to aggressive capacity additions in Asia, and adapts to fluctuating raw material economics, the margin for error is shrinking. Companies that continue to rely on fragmented data sources, outdated market assumptions, or generalized forecasts will face compounding strategic disadvantages. The epoxy resin for PCB market is entering a phase where differentiation will be earned through precision, not just scale.
Worldwide Epoxy Resin for PCB Market
Access to the complete market study offers a tangible advantage. It equips stakeholders with the contextual depth to interpret headline trends, the segmentation clarity to identify where growth is genuinely materializing, and the competitive intelligence to anticipate how rivals are positioning themselves. More importantly, it provides the connective tissue between seemingly disparate developments, linking a capacity expansion announcement in one region to a trade ruling in another, and connecting a raw material price dip in the third quarter to a major price increase announcement in the first quarter of the following year.
For organizations committed to capturing value in this market, the full report is not an optional reference; it is a strategic asset. The complete dataset, competitive benchmarks, and forward-looking scenario analysis are available in the full Worldwide Epoxy Resin for PCB Market study, accessible now on the PW Consulting website. Readers are invited to explore the full publication to obtain the detailed segment breakdowns, precise regional valuations, and actionable recommendations required to navigate the market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resin for PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Rail AC Market Hits $14.05B in 2025, Forecast 6.55% CAGR Through 2032
By PW Consulting, 2026-09-17
Worldwide Rail Air Conditioning Market: Strategic Intelligence for 2026 Decision-Making
As global rail networks accelerate modernization and passenger expectations for comfort and reliability intensify, the rail air conditioning market has emerged as a critical nexus of engineering innovation, regulatory compliance, and commercial opportunity. PW Consulting’s latest industry research delivers a comprehensive, data-driven assessment of this sector, providing executives, procurement leaders, and strategic planners with the actionable intelligence required to navigate a complex 2026 landscape. This study is not a static snapshot; it is a forward-looking strategic compass designed to align capital allocation, product portfolio planning, and competitive positioning with the market’s most consequential trajectories.
Worldwide Rail Air Conditioning Market
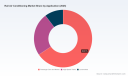
The research is anchored in rigorous historical analysis spanning 2020 through 2025, with a detailed forecast extending to 2032. Over this period, the market has demonstrated consistent expansion, transitioning from a total revenue baseline of approximately 10.8 billion USD in 2020 to an estimated 14.05 billion USD in 2025. The projected trajectory indicates sustained momentum, with the market expected to approach 14.77 billion USD in 2026 and continue scaling toward nearly 22 billion USD by the end of the forecast window. A compound annual growth rate of 6.55 percent underscores the sector’s structural resilience, driven by fleet renewal programs, urban transit expansion, and the integration of next-generation thermal management systems across diverse rail platforms. These figures represent more than aggregate movement; they reflect a fundamental shift in how rail operators conceptualize climate control, energy efficiency, and passenger experience as interdependent operational priorities.
Rail Market
Report Architecture and Operational Utility
PW Consulting’s methodology prioritizes translational insight over raw data compilation. The study is structured to support real-world planning cycles, offering decision-makers a clear pathway from macro trends to tactical execution. The report delivers an integrated examination of market sizing, segmentation dynamics, competitive positioning, and regulatory-technological inflection points, all calibrated to the practical needs of industry stakeholders.
Core Analytical Dimensions
The research dissects the market across multiple structural axes, enabling precise alignment with corporate strategy and operational planning:
- Comprehensive historical tracking and forward-looking revenue modeling that contextualizes growth within broader rail infrastructure investment cycles and fleet modernization timelines
- Analysis of product architecture evolution, including roof-mounted, split, and under-floor configurations, with attention to integration complexity, maintenance profiles, and application-specific performance requirements
- Evaluation of deployment environments spanning passenger cars and metros, high-speed trains, and locomotives, highlighting how thermal load profiles, duty cycles, and operational constraints shape procurement preferences
- Geographic revenue mapping that identifies regional demand intensity, infrastructure maturity, and procurement pathway variations without oversimplifying local market nuances
- Assessment of material supply pressures, including copper price volatility for HVAC heat exchangers and skilled labor cost trajectories, with implications for manufacturing economics and margin management
Strategic Application for 2026 Planning
For executives confronting 2026 budgeting, capacity planning, and technology roadmap decisions, the report functions as an operational bridge between market intelligence and executable strategy. Procurement teams can leverage the segmentation analysis to validate supplier shortlists against application-specific performance thresholds and lifecycle cost expectations. Product development groups gain insight into technological adoption patterns, including inverter-driven compressor architectures, brushless DC motor integration, and low-global-warming-potential refrigerant transitions, enabling prioritization of R&D investments that align with near-term regulatory and operational mandates. Corporate strategy and business development functions benefit from competitive landscape mapping that clarifies positioning, partnership opportunities, and white-space identification across mature and emerging demand centers.
Competitive Landscape and Strategic Positioning
The rail air conditioning sector is characterized by a concentrated yet dynamically competitive environment, where established industrial manufacturers, specialized HVAC integrators, and regional equipment suppliers compete on engineering differentiation, compliance robustness, and global service reach. PW Consulting’s analysis maps this landscape with attention to both market structure and recent corporate activity, providing a realistic view of how leading players are shaping demand and defending share.
Market Concentration and Structural Dynamics
The market exhibits meaningful concentration among top-tier suppliers, with the top three firms collectively representing approximately 42.5 percent of revenue and the top five capturing roughly 58.3 percent. This structure reflects the technical barriers inherent in rail HVAC design, the importance of certified reliability, and the value of long-term operator relationships across multi-year rolling stock programs. At the same time, regional specialization and application-focused expertise continue to create room for nimble suppliers that can deliver tailored solutions for metro networks, high-speed corridors, and locomotive fleets. The competitive environment rewards companies that can combine thermal engineering precision with scalable manufacturing, regulatory compliance, and localized support infrastructure.
Leading Participants and Strategic Differentiation
Several companies define the current competitive rhythm through product innovation, contract execution, and certification readiness:
- Knorr-Bremse maintains a strong position through its HVAC division, supplying roof-mounted and under-floor units for passenger trains worldwide, and recently advanced its portfolio with a next-generation rail HVAC system targeting meaningful energy savings for European metro applications
- Faiveley Transport, operating under Wabtec Corporation, emphasizes modular air conditioning architectures with global installation experience across locomotives, coaches, and urban transit, and has been positioned as a primary HVAC supplier for major Indian Railways train expansions
- Toshiba Carrier Corporation focuses on advanced rail air conditioning units leveraging inverter technology for Japanese Shinkansen and international export projects, with an emphasis on lightweight and low-power designs
- Hitachi delivers integrated rail HVAC systems for high-speed trains and metros, incorporating energy recovery features, and has progressed validation testing for eco-friendly units tied to major high-speed infrastructure programs
- Bombardier Transportation, now part of Alstom, provides custom air conditioning packages for passenger rolling stock with an emphasis on reliability and compliance with EN 14750 standards, reinforced by recent major trainset supply awards in Europe
- Siemens Mobility offers climate control systems for rail applications, including platforms such as Mireo and Desiro, with a clear focus on sustainable cooling technologies and energy-conscious compressor innovation
- Mitsubishi Electric manufactures rail air conditioning equipment with variable refrigerant flow for metro and commuter trains, maintaining active global participation and updated certification coverage for its rail lineup
- Aqua Group produces HVAC systems for railcars, including distributed and centralized unit configurations, serving European and Asian operators with application-flexible designs
- STULZ Air Technology Systems supplies precision air conditioning for rail control rooms and passenger compartments, utilizing modular designs that support integration efficiency and serviceability
- Guangzhou Metro AC Equipment Co., Ltd. stands as a key Chinese supplier of air conditioning systems for urban rail transit, supporting domestic high-speed and metro projects with regionally attuned engineering and manufacturing execution
Recent Commercial and Technological Activity
The competitive picture is further illuminated by recent developments that signal where the market is heading in 2025 and 2026. Product launches emphasizing energy efficiency, contract awards tied to next-generation high-speed fleets, testing validation for environmentally aligned systems, supplier nominations for large-scale national rail programs, and updated compliance certifications all point to a sector in active transition. These events are not isolated milestones; they are indicators of how leading firms are recalibrating portfolios around efficiency, regulatory readiness, and regional program participation. The research synthesizes these moves into a coherent competitive narrative, helping stakeholders interpret which capabilities are likely to command premium positioning in upcoming procurement cycles.
Regulatory, Material, and Technological Forces Shaping 2026
Market trajectory in rail air conditioning is increasingly determined by intersecting external forces. Regulation, raw material economics, and technology substitution are no longer background variables; they are active determinants of cost structure, product design, and supplier selection. The report integrates these dynamics into a unified view of market risk and opportunity.
Compliance and Refrigerant Transition
Rail HVAC systems operate under strict performance expectations, including compliance with EN 14750, which governs air conditioning systems in rail vehicles and mandates reliable performance under extreme temperature conditions ranging from -25°C to +50°C. Beyond baseline performance, the refrigerant landscape is shifting. EU Stage V emission standards for refrigerants require low-GWP alternatives such as R1234yf in new rail HVAC systems from 2025, compelling manufacturers and operators to align product selection with environmental mandates while managing transition complexity. These requirements influence not only design engineering but also sourcing 전략, certification timelines, and lifecycle service planning.
Input Cost Pressures and Manufacturing Economics
Material and labor economics add another layer of strategic consideration. Copper prices for HVAC heat exchangers have risen 15 percent year-over-year to approximately 9,500 USD per tonne, directly affecting production costs for heat exchanger-intensive rail AC configurations. At the same time, skilled HVAC assembly labor costs in Europe averaged 45 EUR per hour in 2025, increasing 8 percent due to workforce shortages. These pressures interact with product architecture decisions, sourcing strategies, and regional manufacturing footprints, making cost resilience and supply chain flexibility critical competitive attributes in 2026 planning.
Technology Substitution and Efficiency Gains
Technological evolution continues to reshape performance expectations. The shift to brushless DC motors in rail AC compressors has been shown to reduce energy use by roughly 25 percent compared with traditional units, offering a clear pathway to operational savings and emissions-aligned performance. Inverter-driven architectures, energy recovery features, and modular integration approaches further expand the design space for manufacturers seeking to differentiate on efficiency without compromising reliability. The research evaluates how these technology trends interact with application requirements, certification frameworks, and operator priorities, enabling stakeholders to anticipate which solutions are likely to gain traction in upcoming procurement and fleet renewal cycles.
Translating Market Intelligence into Strategic Action
PW Consulting’s Worldwide Rail Air Conditioning Market research is designed to support decisive action under uncertainty. The study does not merely describe market size and segmentation; it contextualizes growth within the forces that will shape bidding outcomes, supplier negotiations, technology roadmaps, and regional expansion choices in 2026 and beyond. Executives who engage with the full analysis gain access to detailed segmentation insights, competitive benchmarking, procurement pathway considerations, and forward-looking indicators that connect market scale to strategic execution.
The report’s value lies in its ability to clarify where demand is forming, which technical and regulatory requirements are becoming non-negotiable, how leading suppliers are positioning themselves, and what cost dynamics may influence margin and pricing strategies. By integrating historical performance, forecast trajectory, and current industry developments into a single analytical framework, the research equips stakeholders with the perspective needed to prioritize investments, structure supplier relationships, and align product or procurement strategies with the market’s most durable trends.
For organizations preparing for 2026 planning cycles, the complete dataset, segmentation detail, competitive profiles, and regulatory-technological assessments provide the depth required to move from intuition to evidence-based strategy. PW Consulting’s full market research offers the comprehensive intelligence necessary to inform capital deployment, product planning, and competitive positioning with confidence. Readers seeking the complete segmentation breakdown, company-level analysis, and actionable recommendations are encouraged to access the source report directly, where the full scope of market intelligence is available for strategic review and decision support.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Air Conditioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Foam Market Hits $78.5M in 2025, Projects 17.84% CAGR to $247.74M by 2032
By PW Consulting, 2026-09-17
Navigating the Green Shift: Strategic Insights from the Worldwide Wood Foam Market Research 2026
The global materials landscape is undergoing a seismic transformation. As industries grapple with the dual pressures of regulatory compliance and sustainability mandates, wood foam has emerged from a niche innovation to a critical component in the supply chain of major sectors ranging from packaging to construction. At PW Consulting, we recognize that understanding this trajectory is not merely an academic exercise but a commercial imperative. Our latest comprehensive study, the Worldwide Wood Foam Market research, offers a granular look at this evolving sector, providing the intelligence necessary for stakeholders to navigate the complexities of 2026 and beyond.
This article serves as a strategic preview of our findings. It outlines the macroeconomic forces driving growth, the competitive dynamics reshaping the supply base, and the specific operational insights contained within the full report. Our goal is to equip decision-makers with the context needed to evaluate opportunities in this high-growth market, while highlighting why detailed data access is crucial for precise planning.
Market Trajectory: From Niche to Mainstream
The wood foam market has demonstrated remarkable resilience and acceleration over the past half-decade. Based on historical analysis spanning 2020 through 2025, the sector has moved steadily away from its experimental roots toward established commercial viability. The total revenue generated by the market has seen a consistent upward trend, reflecting a broader industrial shift toward bio-based materials. By the base year of 2025, the market had solidified its position, setting the stage for the forecast period extending to 2032.
Our analysis indicates that the momentum is not slowing down. The forecast period from 2026 to 2032 predicts a robust compound annual growth rate (CAGR) of 17.84%. This growth trajectory suggests that wood foam will capture significant market share from traditional petroleum-based foams. The total market size is projected to expand substantially by the end of the forecast window, signaling a mature acceptance of wood fiber-based solutions in high-volume applications. For investors and corporate strategists, this growth curve represents more than just volume; it indicates a structural change in how materials are sourced, processed, and disposed of globally.
Worldwide Wood Foam Market
The acceleration is driven by a confluence of factors that go beyond simple cost competition. It is rooted in a fundamental reassessment of material lifecycle. As companies face increasing scrutiny regarding their carbon footprints, the appeal of a material derived from sustainably managed forests becomes a strategic asset. The market data underscores that this is not a temporary trend but a long-term reallocation of capital and resources toward renewable feedstocks.
Melamine Foam Market
Regulatory Tailwinds and Raw Material Realities
One of the most critical drivers identified in our research is the regulatory environment. Governments worldwide are tightening restrictions on single-use plastics and non-recyclable packaging materials. In Europe, the Packaging and Packaging Waste Regulation (PPWR) stands out as a pivotal force. This regulation drives demand for fiber-based alternatives like wood foam to replace single-use plastics in packaging. For manufacturers operating in or exporting to the European Union, compliance is no longer optional, and wood foam offers a compliant pathway that aligns with circular economy goals.
Beyond compliance, there is a technical advantage regarding end-of-life scenarios. Wood foam materials are designed for kerbside recyclability in existing paper and cardboard streams, supporting circular economy compliance. This feature differentiates wood foam from many biodegradable plastics that require industrial composting facilities. The ability to integrate into existing waste infrastructure reduces liability for downstream customers and simplifies the value proposition for procurement teams.
On the supply side, the reliance on sustainably sourced Nordic wood fibers from managed forests as the primary renewable feedstock ensures a stable raw material base. Unlike petrochemical feedstocks, which are subject to volatile oil prices and geopolitical instability, wood fiber supplies are managed through established forestry protocols. Furthermore, advanced processes start with wood fibers and water suspension foamed without petrochemical additives, resulting in 100% renewable resource composition. This purity profile is increasingly valuable as brands seek to eliminate hidden plastics from their product portfolios.
Segmentation Dynamics: Where the Opportunity Lies
While our full report delves into precise volumetric and valuation splits, the strategic narrative points to clear dominance in specific areas. The segmentation analysis reveals that certain types of wood foam are outpacing others in adoption rates. Flexible variants are capturing a significant portion of the market attention, driven largely by their versatility in cushioning and protective roles. Rigid variants also hold a substantial position, particularly where structural insulation and lightweight construction are priorities.
Application-wise, the building and construction sector represents a major consumption center. The need for thermal insulation and sustainable building materials aligns perfectly with the properties of wood foam. However, the protective packaging sector is rapidly emerging as a critical growth engine. As e-commerce continues to expand and consumers demand eco-friendly unboxing experiences, the demand for cushioning materials that do not compromise on sustainability is surging. Automotive and transportation applications also contribute to the mix, leveraging the lightweight nature of the material to improve fuel efficiency and reduce vehicle weight.
It is important for strategists to note that regional demand varies significantly based on local regulations and industrial maturity. Europe currently holds a leading position in terms of market share, reflecting its early adoption of sustainability mandates. North America and Asia Pacific are following closely, with distinct growth drivers in each region. North America is seeing growth driven by consumer brand commitments to sustainability, while Asia Pacific is leveraging manufacturing scale and growing domestic demand for green materials. The Rest of the World segment, while smaller currently, presents potential for future expansion as regulatory frameworks evolve globally.
Competitive Landscape: Innovation and Collaboration
The competitive environment in the wood foam market is characterized by a mix of established material giants, specialized research institutes, and niche distributors. Our report provides detailed profiles and strategic assessments of key companies shaping the industry. Leading the charge is Stora Enso, headquartered in Helsinki, Finland. As a primary global producer of Fibrease and Papira wood foam, Stora Enso is setting the benchmark for cellulose and wood fiber-based foam. Their focus on bio-based, recyclable alternatives to polymer foams with cushioning and insulating properties has made them a central figure in the transition away from plastics.
Collaboration is a key theme in this landscape. Nature-Pack serves as an exclusive North American distributor and partner for Stora Enso Fibrease, providing sustainable, recyclable packaging foam solutions as a low-carbon substitute for traditional polymer foams. Similarly, NOVAPOR supplies Stora Enso Fibrease wood foam as sheets, cuttings, punched parts, and finished packaging solutions for protective, insulating, and cushioning applications. This ecosystem approach allows technology developers to focus on production while partners handle regional distribution and customization.
Research and development remain vital. Fraunhofer WKI, based in Braunschweig, Germany, is a research institute developing 100% wood-based foam from wood particles and fibers for thermal insulation, packaging, and lightweight construction applications. Their focus on scalable production processes for rigid boards and flexible mats ensures that the technology remains viable for industrial-scale adoption. On the commercial side, Nefab collaborated on early commercialization of wood foam for eco-friendly fibre-based recyclable packaging, offering fibre-based foam solutions for industrial packaging.
The market concentration indicates a somewhat consolidated environment, with the top firms holding a significant share of revenue. This consolidation suggests that barriers to entry may be high regarding proprietary technology and supply chain integration. However, there are active manufacturers such as Reilly Foam Corporation and JB Polymers, both based in the United States, who are listed as active in the wood foam sector. Their involvement signals that the technology is accessible enough for broader manufacturing participation, provided the right capabilities are in place. Recent developments, such as the continued commercial supply and development of Fibrease and Papira wood foam lines by Stora Enso in early 2025, validate the scalability for plastic phase-out in protective applications. Additionally, capacity expansions in related foam sectors, such as the investment by American Excelsior Company to triple molded urethane production capacity, indicate a broader industry readiness to meet growing demand in foam-based applications.
Inside the Report: Actionable Intelligence for 2026
The Worldwide Wood Foam Market research report is designed to be a practical tool for strategic planning. It goes beyond high-level trends to offer specific data points that can inform budgeting, sourcing, and expansion decisions. The report covers the historical period from 2020 to 2025, providing a solid baseline for understanding how the market reacted to recent economic shocks and policy changes. It then extends the forecast through 2032, allowing for long-term capacity planning.
Readers will find detailed segmentation analysis that breaks down the market by Region, Type, and Application. While we cannot disclose the full granularity here, the report quantifies the revenue contributions of each segment in USD Million. This allows clients to identify which niches offer the highest margin potential or the fastest growth rates. For example, understanding the precise split between flexible and rigid foam helps manufacturers decide whether to invest in flexible mat production lines or rigid board presses.
The report also includes a comprehensive competitive landscape section. We analyze the market concentration, noting that the top three players account for a significant portion of the market revenue. This insight helps new entrants understand the competitive intensity and helps existing players benchmark their position. We also track recent developments and company profiles, ensuring that stakeholders know who is partnering with whom and where capacity is being added.
Furthermore, the research integrates industry context noise into the analysis. This includes specific facts about raw material sourcing, such as the use of sustainably sourced Nordic wood fibers, and regulatory impacts like the EU PPWR. By contextualizing the data within these operational realities, the report helps users assess risks related to supply chain continuity and regulatory compliance. Whether you are looking to invest in production technology, switch materials for packaging, or identify acquisition targets, the data provided is structured to support those specific use cases.
Strategic Imperatives for Decision Makers
As we look toward 2026, the message from the data is clear: wood foam is transitioning from an alternative material to a mainstream solution. The CAGR of 17.84% is not just a number; it represents a window of opportunity for companies that act decisively. For material suppliers, the imperative is to secure supply chains and scale production to meet the anticipated demand surge. For users of foam materials, such as packaging firms and construction companies, the strategic move is to pilot wood foam solutions now to stay ahead of regulatory curves and consumer expectations.
Risk management is also a key component of the strategy. While the growth outlook is positive, reliance on specific feedstocks and regulatory stability requires careful monitoring. The report provides the frameworks to assess these risks. Understanding the market concentration helps in evaluating supplier dependency. Knowing the application splits helps in diversifying revenue streams. The integration of raw material facts and regulatory updates ensures that strategies are built on a foundation of reality rather than speculation.
Ultimately, the Worldwide Wood Foam Market research is an investment in clarity. In a market defined by rapid change and complex sustainability criteria, having access to verified, detailed data is the difference between guessing and strategizing. We invite stakeholders to explore the full report to access the specific regional valuations, application splits, and competitive metrics that will define their success in this evolving landscape.
The transition to sustainable materials is inevitable. The question for industry leaders is no longer if they should adapt, but how quickly they can integrate solutions like wood foam into their operations. With the insights provided in our comprehensive study, PW Consulting aims to be the partner that accelerates that transition, turning market data into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting HDH Titanium Powder Report: Market Hits $524.5M in 2025, Projected 7.2% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Imperatives in the HDH Titanium Powder Market: Navigating Growth and Supply Chain Complexity Through 2032
The global landscape for hydrogenated-dehydrogenated (HDH) titanium powder is undergoing a profound transformation, driven by the simultaneous demands of aerospace defense, medical implant innovation, and the rapid adoption of metal additive manufacturing. For senior leadership and strategic planners, the period between 2026 and 2032 represents a critical window where capacity allocation, supply chain resilience, and purity standardization will dictate market share and profitability. PW Consulting has released a comprehensive market intelligence study designed to equip stakeholders with the actionable foresight required to navigate this high-velocity environment. This analysis serves as an executive overview of the strategic value embedded within our latest HDH Titanium Powder Market research, highlighting the macro-economic trajectories and competitive shifts that will shape decision-making in the coming years.
Macro-Economic Trajectory and Demand Forecasting
Our longitudinal analysis covers historical performance from 2020 through the base year of 2025, with an extensive forecast period extending to 2032. This 13-year view allows us to isolate structural growth trends from short-term volatility. The market demonstrated robust expansion throughout the historical review period, recovering from global logistical disruptions and accelerating as industrial production normalized. By 2025, the total market revenue had firmly established a trajectory that suggests sustained upward momentum.
Looking forward, the forecast model projects a Compound Annual Growth Rate (CAGR) of 7.2 percent across the valuation period. This growth rate is not merely a numerical projection but a reflection of widening application scopes and the substitution of traditional wrought materials in specific high-value sectors. Revenue is expected to climb from approximately 556 million USD in 2026 to over 853 million USD by 2032. For procurement directors and investment committees, this trajectory implies that locking in supply agreements early or investing in capacity expansion before the peak of the growth curve could yield significant competitive advantages. The scale of this expansion suggests that HDH titanium powder is transitioning from a niche material to a strategic commodity essential for advanced manufacturing resilience.
HDH Titanium Powder Market
Segmentation Dynamics and Application Diversification
The demand landscape is fragmented across multiple purity grades and application verticals, each with distinct technical requirements and pricing sensitivities. The market is primarily divided between Commercial Purity (CP) Titanium and Ti-6Al-4V and other alloy grades. While CP titanium continues to hold a substantial share due to its utility in chemical processing and general industrial applications, the alloy segment is witnessing intensified interest from high-performance sectors where mechanical strength and corrosion resistance are paramount.
On the application front, the divergence in usage patterns highlights the versatility of the HDH process. Powder Metallurgy Components remain a traditional stronghold, leveraging the cost-effectiveness of irregular particle shapes. However, Metal Injection Molding (MIM) represents a high-growth vector, driven by the need for complex geometries in medical and consumer goods that traditional machining cannot economically achieve. Industrial additives and chemical applications provide a stable baseline demand, while Surface Coating and Thermal Spray applications offer specialized opportunities for wear resistance and component extension.
It is crucial for strategists to understand that these segments do not grow in isolation. Cross-segment competition for high-purity supplies is intensifying. For instance, the medical sector's requirement for low-oxygen and low-impurity profiles often competes directly with aerospace specifications. Our report details the specific volume flows and value drivers within each segment without exposing the proprietary granularity that would compromise client confidentiality, providing instead the relative weight and growth potential of each vertical to inform portfolio strategy.
Competitive Landscape and Corporate Consolidation
The industry structure is characterized by a moderate concentration, with the top three players controlling approximately 42.5 percent of the market and the top five commanding roughly 58.3 percent. This concentration indicates that while there is room for specialized entrants, scale and integrated supply chains remain powerful moats. The competitive field is globally distributed, with significant hubs in Asia Pacific, North America, and Europe, though Asia dominates in terms of total market revenue contribution.
Key Strategic Players and Operational Focus
Several key enterprises define the current competitive boundaries, each employing distinct strategies to secure market position:
Titanium Powder Market
- Toho Titanium Co., Ltd. and OSAKA Titanium Technologies Co., Ltd. represent the Japanese high-quality heritage, focusing on low impurity levels suitable for sputtering targets, getters, and high-grade powder metallurgy. Toho Titanium's recent corporate integration with JX Advanced Metals Corporation, effective June 2026 following a share exchange agreement, signals a move toward consolidated resource management and potentially expanded R&D capabilities under a larger corporate umbrella.
- Kymera International and ATI Inc. anchor the North American supply chain with a focus on customizable particle size distributions down to 45 microns. ATI Inc.'s expanded long-term agreement with Boeing in July 2025 reinforces the critical link between powder suppliers and major aerospace primes, ensuring steady demand for high-performance grades.
- Chinese manufacturers, including Lasting Titanium Industry Co., Ltd., AEM Metal, Baoji Titanium Industry Co., Ltd., and MTCO, form a significant production bloc. Lasting Titanium, for example, has historically accounted for a vast majority of China's titanium powder exports, leveraging proprietary hydride-dehydride processes to serve global aerospace and medical markets. Their ability to offer wide PSD options and competitive pricing pressures margins across the global supply chain.
- VSMPO-AVISMA Corporation and Höganäs AB round out the global presence, with VSMPO supplying aerospace-grade powders compliant with international standards and Höganäs offering broad application support for additive manufacturing and coatings.
Recent certification updates, such as North Titanium Industry Co., Ltd.'s ISO Quality Management System achievement in January 2025 for high-purity HDH powder, underscore the industry-wide shift toward rigorous quality assurance as a differentiator. Understanding the specific capacity constraints, geographical footprints, and strategic partnerships of these players is essential for supply chain risk assessment.
Supply Chain Vulnerabilities and Regulatory Pressures
Beyond the pure market dynamics, external factors exert substantial pressure on pricing and availability. The HDH production process relies heavily on titanium sponge feedstock, which is converted via hydrogenation to embrittle, crushed, and subsequently dehydrogenated. This technical pathway enables the production of low-cost irregular powders suitable for powder metallurgy and thermal spraying, but it also ties the powder market directly to the volatility of the sponge market.
Geopolitics and Raw Material Security
A critical strategic consideration is the geography of raw material origin. China controls approximately 65 percent of global titanium sponge capacity. This dominance creates inherent supply chain vulnerabilities for HDH powder production, particularly for North American and European manufacturers reliant on imported feedstock. The potential for export controls or tariffs on titanium materials introduces a risk premium that must be factored into long-term budgeting and sourcing strategies.
Furthermore, national security concerns regarding titanium supply have been highlighted in regulatory contexts. The U.S. Department of Commerce Section 232 investigation noted that reliance on foreign titanium sponge imports threatens national security, especially given the lack of domestic commercial production since 2020. These geopolitical undercurrents suggest that future policy interventions could reshape trade flows, incentivizing domestic capacity development or friend-shoring arrangements.
Cost Structures and Regulatory Compliance
Pricing dynamics also play a pivotal role in market adoption. HDH titanium powders typically offer a more cost-competitive alternative compared to gas-atomized spherical powders, with price points varying based on grade, purity, and particle size. This cost advantage drives adoption in powder metallurgy and thermal spray applications where spherical morphology is not strictly required. However, as specifications tighten for medical and aerospace uses, the cost differential may narrow.
Regulatory compliance adds another layer of complexity. For medical implants, HDH titanium powder must comply with standards such as ISO 23301 for sintered titanium materials and products for surgical implants, alongside ASTM specifications for powder metallurgy shapes. Adherence to these standards is not optional but a prerequisite for market entry in high-value segments. Our report analyzes how compliance costs are distributed across the value chain and which regions are most susceptible to regulatory shifts.
Strategic Value of the 2026 Analysis
In an environment defined by volatility and rapid technological iteration, generic market data is insufficient for strategic planning. The PW Consulting HDH Titanium Powder Market report provides the depth required to make informed decisions regarding capacity investment, supplier qualification, and market entry. We have synthesized historical performance, forward-looking forecasts, and competitive intelligence into a cohesive narrative that addresses the specific pain points of procurement, strategy, and R&D leadership.
The analysis avoids superficial aggregation, instead offering a nuanced view of how segmentation splits interact with regional dynamics and regulatory frameworks. We examine how the concentration of market power among key players influences negotiation leverage and how recent corporate developments, such as the integration of major Japanese producers or contract expansions with aerospace primes, signal shifts in supply stability.
Furthermore, the report contextualizes the 7.2 percent CAGR not just as a growth statistic but as a series of milestones that require proactive management. Stakeholders will gain insights into when specific application segments are projected to accelerate, allowing for targeted marketing and production planning. The interplay between raw material costs, geopolitical risks, and technical standards is mapped to help organizations build resilient supply chains that can withstand external shocks.
Conclusion: Positioning for the Next Cycle
The HDH titanium powder market is poised for significant evolution over the next decade. The convergence of aerospace demand, medical innovation, and the cost efficiencies of powder metallurgy creates a fertile ground for growth, but this growth is contingent on navigating complex supply chains and regulatory landscapes. The 2026 baseline represents a pivotal moment where early movers can secure advantages in sourcing and technology partnerships.
PW Consulting's comprehensive study is designed to be the cornerstone of this strategic planning process. By revealing the underlying currents of market concentration, regional dependencies, and application-specific growth vectors, we empower organizations to move beyond reactive decision-making. The full intelligence contained within the report provides the granular detail necessary to refine forecasts and validate assumptions against the latest industry developments.
For leaders committed to securing a competitive position in the titanium value chain, the time to act on these insights is now. We invite you to explore the full depth of our findings to understand how the 2026-2032 trajectory aligns with your specific organizational goals and risk tolerance. The complete market intelligence is available through our secure release portal.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High Voltage System Market to Hit $247B by 2032, Growing at 18.64% CAGR
By PW Consulting, 2026-09-17
Unlocking the Currents of Growth: Strategic Intelligence for the Global High Voltage System Market (2026-2032)
The global energy infrastructure is undergoing a paradigm shift. As nations race to decarbonize grids and accommodate the surging power demands of artificial intelligence data centers and electric mobility, the high voltage system market stands at the forefront of this transformation. At PW Consulting, we recognize that navigating this landscape requires more than general industry knowledge; it demands precise, data-backed strategic intelligence. Our latest report, Worldwide High Voltage System Market, offers a comprehensive roadmap for stakeholders aiming to capitalize on the opportunities defining the next decade.
This market research is not merely a collection of statistics. It is a strategic instrument designed to inform capital allocation, risk assessment, and competitive positioning in 2026 and beyond. With a projected Compound Annual Growth Rate (CAGR) of 18.64% from 2026 to 2032, the sector is experiencing exponential expansion. The total market revenue, valued at approximately 74,550.0 Million USD in the base year 2025, is forecasted to surge toward 247,030.12 Million USD by 2032. This trajectory underscores a critical reality: the window to secure supply chains, forge partnerships, and enter key territories is narrowing. Decision-makers need to understand the magnitude of this expansion without getting lost in the noise of fragmented data sources.
Macro Trends Driving the 18.64% CAGR
The velocity of growth in the high voltage sector is fueled by converging macro trends. Historically, the market has demonstrated resilience and acceleration. From 2020 to 2025, revenue climbed from roughly 22,450.12 Million USD to the aforementioned 74,550.0 Million USD. This five-year historical performance sets the stage for the forecast period, where the compounding effect of renewable integration, grid modernization, and cross-border energy trade will drive figures even higher. By 2028, the market size is expected to breach 136,430.59 Million USD, and by the end of the decade in 2030, it will approach 196,261.41 Million USD.
Several underlying dynamics are propelling this surge. Firstly, the transition to high voltage direct current (HVDC) technologies is becoming standard for long-distance bulk power transfer and offshore wind integration. Traditional alternating current (AC) systems are increasingly unable to handle the efficiency requirements of modern renewable energy corridors. Secondly, the electrification of transport and industry is placing unprecedented load on transmission networks, necessitating upgrades to high voltage infrastructure. Thirdly, geopolitical energy security concerns are driving nations to invest in independent, robust grid capabilities, further stimulating demand for high voltage components and systems.
However, these opportunities are tempered by supply chain complexities. Industry data indicates that lead times for critical components, such as large power transformers, have extended significantly. Prices for these units have risen approximately 77% since 2019, driven by raw material costs including steel and copper. Understanding how these cost pressures impact overall market revenue and project viability is essential for financial planning. Our research dissects these cost drivers to help organizations anticipate budgeting needs and negotiate better terms with suppliers.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of established global giants and specialized regional players. Concentration ratios indicate a moderately consolidated environment where strategic alliances and technological superiority determine market share. The CR3 stands at 38.5%, while the CR5 reaches 52.1%, suggesting that while there are dominant forces, there remains ample room for niche players and regional specialists to flourish.
Key enterprise players are actively shaping the market through capacity expansion and landmark contract wins. Hitachi Energy, headquartered in Zurich, continues to strengthen its manufacturing footprint, including a significant investment exceeding 1 billion USD in U.S. manufacturing expansion announced in September 2025. This move targets high voltage grid infrastructure needs, including those for AI data centers. Similarly, GE Vernova, based in Cambridge, Massachusetts, has secured major contracts, such as the consortium award with Seatrium for the BalWin5 2.2 GW offshore HVDC grid connection in the German North Sea in December 2025. These moves highlight the strategic importance of offshore wind transmission.
In the Asia-Pacific region, companies like TBEA Co., Ltd. and NR Electric Co., Ltd. are expanding their influence with HVDC converter equipment and control systems. Meanwhile, European cable specialists such as Prysmian Group, Nexans, and NKT A/S are critical to the submarine and land interconnection segments. NKT, for instance, secured 2 billion Euro contracts with SSEN Transmission in January 2026 for 525 kV HVDC transmission links in Scotland. Sumitomo Electric Industries and Toshiba Energy Systems & Solutions Corporation are also prominent in providing cables and transformers for bulk power applications.
High Voltage Cables Market
Our report provides detailed profiles on these entities, analyzing their strategic moves, technological portfolios, and regional strengths. However, the specific revenue contributions, exact market shares, and proprietary partnership networks are detailed within the full study. Access to this granular competitive intelligence allows clients to identify potential collaborators, assess competitor vulnerabilities, and refine their own go-to-market strategies.
Segmentation Insights: Components, Voltage, and Geography
Understanding where value is generated within the high voltage system market is crucial for targeted investment. The market is segmented by component, voltage level, and region, each presenting unique growth vectors. Among components, traction inverters and battery management systems represent significant portions of the revenue stream, reflecting the electrification trend in transport and energy storage. On-board chargers, DC-DC converters, and high voltage connectors and cabling also constitute vital parts of the ecosystem.
Voltage level segmentation reveals a bifurcation between standard 400V to 600V systems and the emerging above 600V (800V architecture) systems. While the former currently holds a larger share of the market revenue, the latter is poised for accelerated adoption as efficiency standards tighten and power demands increase. The shift toward higher voltage architectures is particularly relevant for automotive and industrial applications where energy density and transmission efficiency are paramount.
Geographically, the market exhibits varied growth patterns. Asia Pacific remains a dominant region in terms of market value, driven by rapid industrialization and renewable energy installations. Europe and North America follow, with strong regulatory pushes for grid modernization and decarbonization. The Rest of the World segment also presents emerging opportunities as developing nations upgrade their transmission infrastructure. While the aggregate regional values are substantial, the specific percentage contributions and localized growth rates are reserved for the full report to ensure clients rely on our comprehensive analysis rather than partial data points.
Our segmentation analysis goes beyond top-line numbers. We explore the inter dependencies between components and voltage levels, identifying which combinations offer the highest margin potential and fastest deployment cycles. This granular view is essential for component manufacturers and system integrators looking to optimize their product portfolios.
Regulatory and Operational Dynamics Shaping 2026
Policy and regulation are as influential as technology in the high voltage sector. Governments are increasingly intervening to streamline project development and fund innovation. For instance, the U.S. Department of Energy selected four projects totaling 11 million USD under the IDEAL HVDC program in November 2024 to develop high-performance, low-cost HVDC converters. Such initiatives signal a long-term commitment to reducing the cost barrier of high voltage transmission.
Operational milestones are also accelerating. The New England Clean Energy Connect 1,200 MW high-voltage direct current transmission line from Hydro-Quebec began commercial operations on January 16, 2026. This event marks a significant step in cross-border renewable energy integration. Furthermore, regulatory bodies are adapting to infrastructure needs; Colorado enacted legislation allowing co-location of high voltage transmission lines within state highway rights-of-way to streamline development. These regulatory shifts reduce development timelines and lower soft costs, directly impacting project economics.
Grid operators are also planning aggressively. TenneT's Onshore and Offshore Grid Investment Plans 2026 outline multiple high voltage grid expansion projects, though they note longer realization times for new substations and connections. This tension between ambitious investment plans and execution realities creates a complex environment for suppliers. Understanding the timing and scale of these grid plans is vital for aligning production capacity and sales forecasts. Our report integrates these regulatory and operational updates to provide a realistic view of market accessibility and risk.
Why This Report is Indispensable for 2026 Decision-Making
In a market growing at nearly 19% annually, hindsight is insufficient. Leaders need foresight. The Worldwide High Voltage System Market report is designed to provide that foresight. It combines historical data integrity with forward-looking forecasts that account for technological shifts, regulatory changes, and competitive maneuvers.
For investors, the report offers clarity on where capital is most likely to yield returns, highlighting high-growth segments and regions. For manufacturers and suppliers, it provides actionable intelligence on demand forecasting, supply chain vulnerabilities, and customer expectations. For policymakers and grid operators, it offers a benchmark against global trends to validate domestic strategies.
Worldwide High Voltage System Market
The depth of analysis covers over 15 key companies, detailed segmentation across components and voltage levels, and a thorough examination of market dynamics including raw material constraints and regulatory frameworks. While the summary provides a sense of the scale—highlighting the jump from 74,550.0 Million USD in 2025 to a projected 247,030.12 Million USD by 2032—the specific strategic recommendations, normalized data tables, and executable insights require the full document.
We invite industry leaders, investors, and strategy teams to access the complete Worldwide High Voltage System Market research. In an era where energy infrastructure defines economic resilience, having the right data at the right time is the ultimate competitive advantage. PW Consulting delivers the intelligence necessary to navigate the high voltage currents of the future.
For detailed analysis of this topic, please visit the official page: Worldwide High Voltage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trichomonas Rapid Testing Market to Hit $1.05B by 2032, 6.3% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Half-Decade: Inside the Worldwide Trichomonas Rapid Testing Market
The landscape of infectious disease diagnostics is undergoing a structural shift, driven by the convergence of rapid molecular innovations, evolving regulatory frameworks, and a heightened global focus on sexual health. For stakeholders navigating the Trichomonas vaginalis testing sector, understanding the trajectory of this market is no longer optional—it is a critical component of strategic planning. PW Consulting's latest comprehensive study, the Worldwide Trichomonas Rapid Testing Market report, offers a definitive roadmap for the period spanning 2026 through 2032. This article serves as a strategic briefing, outlining the macro-environmental drivers, competitive undercurrents, and the actionable intelligence embedded within our full analysis, designed to empower executive decision-making in 2026 and beyond.
A Market Poised for Sustained Expansion
Historical performance provides the baseline for any robust forecast. The global revenue for Trichomonas rapid testing demonstrated consistent growth between 2020 and 2025, reflecting the steady adoption of point-of-care solutions and the increasing prevalence of screening initiatives. As the market moves into the forecast window starting in 2026, the revenue trajectory indicates a continuation of this upward momentum, with significant valuation milestones expected to be reached by the end of the decade.
Our analysis projects that the market will expand to reach a substantial valuation by 2032, underpinned by a compound annual growth rate (CAGR) of 6.3 percent over the forecast period. This growth rate is not merely a statistical projection; it reflects the compounding effect of technological maturation, expanded test indications, and the integration of trichomoniasis screening into broader sexual health protocols. For 2026, the year serves as a pivotal inflection point, bridging the established baseline of 2025 with the accelerated growth phases anticipated through 2032. The revenue expansion from the 2025 baseline underscores the momentum that market participants must capitalize on immediately to secure competitive positioning for the remainder of the decade.
Navigating the Segmentation Architecture
Understanding the "where" and "how" of market value is essential for resource allocation and product strategy. The market is delineated across multiple dimensions, each presenting distinct opportunities and challenges for manufacturers, distributors, and service providers.
Geographic Value Distribution
The global market is geographically dispersed, with distinct regional growth profiles shaped by healthcare infrastructure, reimbursement policies, and disease prevalence. North America continues to represent a significant portion of the global revenue, driven by advanced diagnostic adoption and established clinical guidelines. Europe follows as a major contributor, characterized by robust public health frameworks and increasing awareness campaigns. Asia Pacific presents a dynamic growth corridor, where expanding healthcare access and rising diagnostic demands are creating new avenues for market penetration. Latin America and the Middle East and Africa, while currently representing smaller shares of the global total, harbor latent demand that is gradually being unlocked by improved distribution networks and targeted public health interventions. Our detailed regional analysis in the full report dissects these dynamics, revealing the specific growth vectors and infrastructure dependencies that define each territory. Stakeholders seeking to expand their footprint will find granular insights into the regulatory and economic factors influencing adoption rates across these diverse markets.
Rapid Influenza Diagnostic Test (RIDT) Market
Technological Paradigms: Antigen vs. Molecular
The test type segmentation reveals a competitive interplay between rapid antigen kits and rapid nucleic acid amplification tests (NAATs). Rapid antigen kits dominate the volume and revenue landscape, favored for their speed, ease of use, and suitability for point-of-care and resource-limited settings. These assays provide qualitative detection of Trichomonas vaginalis antigens from vaginal specimens, delivering actionable results within minutes. On the other hand, rapid NAATs are carving out a high-value niche, particularly in settings demanding superior sensitivity and specificity, or where molecular confirmation is required. The evolution from traditional lateral flow formats to isothermal molecular platforms is reshaping the technical requirements of end-users. The full report provides a deep dive into the performance characteristics, market acceptance, and pricing dynamics of each technology class, enabling clients to assess the strategic fit of their product portfolios against the evolving technical preferences of the diagnostic community.
End-User Ecosystems and Adoption Channels
Where testing occurs fundamentally influences product design, procurement strategies, and market access. Diagnostic laboratories remain a core pillar of demand, leveraging high-throughput capabilities and specialized expertise to process large volumes of specimens. Hospitals and clinics represent another critical channel, where rapid turnaround times directly impact patient management and treatment initiation. Notably, the segment encompassing home care and self-testing is gaining prominence, reflecting a broader trend toward patient empowerment and decentralized care. The rise of self-collection and at-home diagnostic options is altering the traditional provider-centric model, introducing new considerations for product usability, regulatory clearance, and consumer education. Our market study maps the revenue contributions and growth trajectories of these end-user categories, offering strategic guidance on channel mix optimization and partnership opportunities that align with the shifting patterns of healthcare delivery.
Competitive Dynamics and Key Player Profiles
The competitive environment is defined by a concentrated group of specialized players, each leveraging unique technological advantages and market positions. Our report provides in-depth profiles of the key companies shaping the industry, analyzing their product portfolios, strategic moves, and competitive strengths.
- Sekisui Diagnostics, based in Burlington, MA, and formerly associated with Genzyme, holds a differentiated position with the OSOM Trichomonas Rapid Test. This assay is recognized as the only CLIA-waived lateral flow antigen detection test for Trichomonas vaginalis from vaginal swabs, delivering results in approximately 10 minutes with high agreement rates compared to culture and wet mount methods. The CLIA-waived status is a strategic asset, broadening the scope of testing sites and facilitating integration into diverse clinical workflows. Additionally, the test is associated with Medicare reimbursement under relevant procedure codes for infectious agent antigen detection, a factor that significantly influences adoption in the US healthcare system.
- Liming Bio, headquartered in China, manufactures the StrongStep Trichomonas Vaginalis Antigen Rapid Test, focusing on the qualitative detection of antigens from vaginal specimens. As a manufacturer in a key manufacturing hub, Liming Bio contributes to the global supply of affordable rapid testing solutions, catering to markets where cost-effectiveness and accessibility are paramount.
- Vitrosens Biotechnology, operating from Turkey, provides the RapidFor Trichomonas Vaginalis Rapid Test Kit as part of its broader suite of rapid diagnostic solutions. The company represents the growing capabilities of the Turkish diagnostic sector, offering products that address the need for reliable and rapid detection in various healthcare settings.
- QuidelOrtho, based in San Diego, CA, offers the Solana Trichomonas Assay, an isothermal molecular test, and previously the AmpliVue Trichomonas assay. These solutions target the detection of Trichomonas vaginalis nucleic acids from vaginal and urine specimens in women, positioning QuidelOrtho at the intersection of rapid turnaround and molecular accuracy.
- Cepheid, headquartered in Sunnyvale, CA, markets the GeneXpert TV assay, a moderately complex rapid molecular test capable of detecting Trichomonas vaginalis from a wide range of specimen types, including vaginal swabs, endocervical swabs, urine from both female and male patients, with results available in less than an hour. The GeneXpert platform's versatility and widespread installation base provide Cepheid with a strong foothold in hospital and reference laboratory settings, particularly where multiplex testing and high specificity are required. The assay is FDA-cleared for detection in female urine, endocervical swabs, patient-collected or clinician-collected vaginal specimens, and male urine specimens, aligning with comprehensive CDC STI treatment guidelines.
Beyond individual company profiles, the full report analyzes the broader competitive structure, noting that the top three players account for over half of the market revenue, while the top five collectively represent more than 72 percent. This concentration highlights the dominance of established entities with specialized product clearances and strong distribution networks, while also signaling opportunities for emerging players who can introduce disruptive technologies or expand into underpenetrated geographic segments.
Industry Dynamics: Regulation, Reimbursement, and Clinical Validation
The market's evolution is heavily influenced by regulatory milestones and clinical evidence that shape adoption patterns. Recent developments underscore the pace of innovation and the tightening of evidentiary standards. In March 2025, Visby Medical received FDA clearance for its Sexual Health Test, a significant event that granted marketing authorization for an at-home diagnostic test for STIs, including Trichomonas vaginalis, in women with or without symptoms. This clearance also included a CLIA waiver for point-of-care PCR testing, signaling a potential paradigm shift toward highly accurate molecular testing accessible outside traditional laboratory settings. Such regulatory breakthroughs lower barriers to entry for decentralized testing and expand the addressable market for companies aligned with these technological capabilities.
Clinical validation continues to reinforce the utility of rapid testing modalities. A meta-analysis published in July 2025 in the Journal of Lower Genital Tract Disease evaluated rapid antigen tests for trichomoniasis, reporting a pooled sensitivity of 87.0 percent and specificity of 98.3 percent across 5,884 samples. These performance metrics provide robust support for the use of antigen-based rapid tests in screening and diagnostic algorithms, balancing the need for speed with acceptable accuracy. For product developers and market strategists, such data points are critical for substantiating claims, guiding healthcare provider education, and influencing procurement decisions.
Regulatory and reimbursement landscapes further complicate the strategic picture. The distinction between CLIA-waived and moderately complex tests affects where and how assays can be deployed, influencing the total addressable market for each product. Reimbursement pathways, including associations with Medicare procedure codes for infectious agent antigen detection, directly impact the financial viability of testing programs and the willingness of providers to adopt specific solutions. Our report dissects these dynamics, providing clients with a clear understanding of the regulatory hurdles, reimbursement opportunities, and compliance requirements that will define market access in the coming years.
Strategic Imperatives for 2026 Decision-Makers
The insights contained within the Worldwide Trichomonas Rapid Testing Market report are designed to translate complex market data into actionable intelligence for 2026. As the industry moves past the 2025 baseline, several strategic imperatives emerge for stakeholders aiming to maximize their position in the growing market.
For manufacturers, the divergence between antigen and molecular technologies presents a critical portfolio strategy question. The sustained demand for rapid, CLIA-waived antigen tests suggests continued relevance for lateral flow solutions, particularly in decentralized and resource-constrained settings. Simultaneously, the growth of molecular assays and the emergence of at-home PCR testing indicate that investment in nucleic acid detection platforms may offer higher-margin opportunities and alignment with the trend toward higher diagnostic accuracy. Companies must evaluate their R&D pipelines, manufacturing capabilities, and regulatory strategies against these dual tracks to ensure they capture value across the spectrum of testing needs.
For distributors and service providers, understanding the geographic and end-user segmentation is vital for targeting go-to-market efforts. The concentration of revenue in North America and Europe requires sustained commitment to these mature markets, where competition is fierce and differentiation depends on service quality, reimbursement support, and clinical evidence. Conversely, the growth potential in Asia Pacific and other emerging regions demands a nuanced approach that accounts for local healthcare infrastructure, pricing sensitivities, and regulatory environments. Tailoring distribution partnerships and product offerings to the specific needs of diagnostic laboratories, hospitals, clinics, and the burgeoning self-testing segment can unlock incremental growth.
Investors and financial analysts will find value in the market concentration data and growth projections, which highlight the stability provided by leading players while also identifying the potential for disruption. The high market share held by the top firms suggests barriers to entry, but recent regulatory clearances for innovative at-home and point-of-care molecular tests demonstrate that new entrants can gain traction by addressing unmet needs in convenience and accessibility. Monitoring the clinical evidence base, such as the sensitivity and specificity data from recent meta-analyses, is essential for assessing the long-term viability of different testing technologies and the competitive moats of incumbent suppliers.
Worldwide Trichomonas Rapid Testing Market
Conclusion: Unlocking the Full Strategic Picture
The Worldwide Trichomonas Rapid Testing Market is at a juncture where historical growth, technological innovation, and regulatory evolution converge to create a dynamic environment for the next seven years. The projected revenue expansion to over 1 billion USD by 2032, supported by a 6.3 percent CAGR, signals a market with substantial opportunities for those equipped with the right intelligence. However, capturing these opportunities requires more than a high-level overview; it demands a granular understanding of segmentation flows, competitive vulnerabilities, regulatory nuances, and the specific dynamics that will drive adoption across regions and end-user groups.
PW Consulting's full market study provides the depth and precision required for confident strategic planning. The report delivers comprehensive segmentation analysis, detailed company profiles, an assessment of market concentration, and an exploration of the key dynamics shaping the industry. It equips executives, product leaders, and investors with the data necessary to forecast demand, optimize portfolios, identify partnership opportunities, and navigate the complexities of the global diagnostic landscape. To access the complete dataset, regional breakdowns, and the full suite of strategic analyses that will inform your 2026 decisions and beyond, we invite you to explore the full report on our website. The complete intelligence is available to guide your strategy with clarity and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Trichomonas Rapid Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pharmaceutical Dyes Market to Reach $1.23B by 2032 Amid 5.52% CAGR
By PW Consulting, 2026-09-17
Strategic Color: Navigating the Pharmaceutical Dyes Market Through 2032
In the highly regulated and technically demanding pharmaceutical industry, colorants are far more than aesthetic additions. They serve as critical quality identifiers, aid in patient compliance, and play a vital role in brand differentiation and counterfeit prevention. As the global pharmaceutical landscape shifts toward more complex drug delivery systems and heightened regulatory scrutiny, the market for pharmaceutical dyes has entered a new phase of strategic importance. PW Consulting's latest Worldwide Pharmaceutical Dyes Market research provides a comprehensive evaluation of this evolving sector, offering actionable intelligence for stakeholders looking to optimize supply chains, innovate product portfolios, and capture growth opportunities from 2026 through 2032.
This report serves as an essential compass for pharmaceutical manufacturers, excipient suppliers, contract development and manufacturing organizations (CDMOs), and investors. By synthesizing historical performance data with forward-looking forecasts, it highlights the intersection of technological innovation, regulatory changes, and shifting consumer preferences that will define market dynamics over the next decade.
Historical Trajectory and Forecasted Growth
Understanding where the market has been is crucial to anticipating where it is headed. Analysis of historical data from 2020 to 2025 reveals a period of steady expansion, driven by increasing demand for orally administered medications and a growing emphasis on patient-centric drug design. The global market reached a valuation of approximately 844.47 million USD in the base year of 2025, marking significant progress from levels observed just five years prior.
Looking ahead, the forecast period from 2026 to 2032 projects continued momentum. The market is expected to surpass the 900 million USD threshold in 2026, reflecting an accelerating pace of adoption in emerging therapeutic areas. By the end of the forecast window in 2032, revenue is projected to approach 1.23 billion USD. This growth path corresponds with a compound annual growth rate of 5.52 percent, signaling a resilient demand structure that is somewhat insulated from broader macroeconomic volatility. For strategic planners, this trajectory suggests that pharmaceutical colorants represent a stable, growth-oriented segment within the broader chemical and healthcare values chain.
Material Diversification: Synthetic versus Natural Solutions
The composition of the market reflects a complex balancing act between performance, cost, and regulatory compliance. Synthetic dyes remain the dominant force, leveraging their consistency, intensity, and well-established compatibility with various manufacturing processes. These materials are particularly critical for applications requiring precise color matching and stability under stringent processing conditions, such as high-shear tablet coating.
However, the segment analysis indicates a notable and accelerating shift toward natural alternatives. As clean-label initiatives expand beyond food and beverage into pharmaceutical formulations, manufacturers are increasingly seeking pigments derived from fruits, vegetables, and other natural sources. This trend is not merely a marketing preference; it is increasingly driven by regulatory expectations in key markets like Europe and the United States, where origin transparency and perceived safety are becoming key differentiators. Pigments and lakes also maintain a significant presence, particularly in specialized applications where solubility characteristics dictate formulation choices. The interplay between these material categories will define competitive positioning, as suppliers invest in R&D to enhance the stability and performance profiles of natural options to rival their synthetic counterparts.
Application Drivers Across Dosage Forms
The demand for pharmaceutical dyes is heavily influenced by the mode of drug administration. Oral solid dosage forms continue to represent the largest application segment, underscoring the enduring dominance of tablets and capsules in global pharmacotherapy. In this context, dyes are indispensable for coating technologies that protect active ingredients, control release profiles, and enhance swallowability and visual identification.
Beyond solids, liquid and semi-solid formulations maintain a substantial share, catering to pediatric, geriatric, and dysphagia populations where ease of administration is paramount. Topical and ophthalmic preparations represent a specialized but high-value niche, where purity standards and light stability are particularly critical. The variation in application requirements means that a one-size-fits-all supply strategy is rarely viable. Successful market participants must align their production capabilities with the specific technical demands of each dosage form, ensuring compliance with monographs such as USP, NF, and Ph. Eur. across all product lines.
Regional Dynamics and Supply Chain Considerations
Geographically, the market exhibits distinct characteristics shaped by local manufacturing capabilities, regulatory environments, and healthcare infrastructure. North America remains a primary revenue contributor, supported by a robust domestic pharmaceutical industry and stringent quality expectations that favor established, compliant suppliers. Europe follows closely, with demand driven by strong generic drug markets and a regulatory framework that increasingly emphasizes sustainability and natural ingredients.
Asia Pacific represents a dynamic growth engine, characterized by expanding manufacturing bases and rising domestic consumption. Latin America and the Middle East and Africa collectively form an emerging frontier, where healthcare access improvements and localized production initiatives are gradually increasing volume demand. For multinational corporations, these regional nuances necessitate a flexible supply chain approach. Recent industry observations highlight that geopolitical factors and raw material availability can introduce significant volatility. For instance, fluctuations in key feedstock prices, such as aniline, have impacted cost structures for azo dye production, while regulatory adjustments in major markets have forced rapid compliance adaptations. Companies that maintain diversified sourcing strategies and invest in regional inventory buffers are better positioned to navigate these disruptions.
Competitive Landscape and Consolidation Trends
The market structure reflects a moderate level of concentration, with leading players holding significant share through technical expertise, regulatory certifications, and long-standing relationships with pharmaceutical clients. The competitive environment is characterized by a mix of large, diversified chemical corporations and specialized niche manufacturers. Key entities such as Sensient Technologies Corporation, Clariant AG, BASF SE, GNT Group, Kolor Jet Chemical Pvt Ltd, and Sun Chemical Corporation illustrate the breadth of capabilities present in the sector.
Sensient Technologies Corporation, based in Milwaukee, USA, continues to strengthen its position through product innovation, recently introducing advanced color dispersions designed to enhance stability in demanding coating processes. Clariant AG, headquartered in Switzerland, has focused on expanding its certification footprint, achieving Halal certification for expanded ranges of iron oxide pigments to access broader international markets. BASF SE, a major player from Germany, has invested in capacity expansion at key sites to meet rising demand for pharmaceutical-grade iron oxides and other colorants certified across global pharmacopeias. Meanwhile, GNT Group from the Netherlands has carved out a distinctive niche by specializing in natural dyes derived from fruits and vegetables, catering to the growing clean-label trend in both Europe and the USA. Manufacturers like Kolor Jet Chemical in India and Sun Chemical in the USA further diversify the landscape by providing compliant dyes and lakes with global certifications, including Halal and Kosher options, to serve varied market requirements.
Recent corporate activities underscore the strategic priorities shaping the landscape. Product launches focusing on enhanced stability and performance, certification updates to meet religious and cultural standards, and capacity expansions to secure supply continuity are recurrent themes. The competitive intensity is further amplified by the fact that market concentration, as measured by leading firms, reflects a market where differentiation through quality, compliance, and innovation is essential to maintaining margins.
Regulatory Pressures and Technical Standards
Regulatory compliance is not a static backdrop; it is an active driver of market evolution. Pharmaceutical dyes operate within a tightly controlled framework governed by pharmacopeial monographs and regional regulations. Recent updates have raised the bar for quality and safety. The European Union's regulation lowering permitted lead levels in pharmaceutical iron oxide dyes required manufacturers to rapidly adjust sourcing and purification processes. Similarly, updates to USP monographs introduced stricter light stability testing for aluminum lake dyes, compelling formulators and suppliers to validate performance under more rigorous conditions.
Worldwide Pharmaceutical Dyes Market
Textile Dyes Market
Beyond product specifications, regulatory enforcement actions also influence market behavior. Increased scrutiny by US FDA on import compliance for certain dyes has led to higher rejection rates for non-conforming shipments, reinforcing the importance of supplier qualification and quality assurance systems. For pharmaceutical companies, these dynamics mean that the dye supply chain must be treated as a critical quality attribute component. Risk mitigation requires deep vetting of suppliers, rigorous testing protocols, and agile responsiveness to regulatory change. This environment favors established players with robust compliance infrastructures and creates barriers to entry for less equipped competitors.
How PW Consulting's Report Supports Strategic Decision-Making
In a market defined by technical complexity, regulatory flux, and shifting consumer expectations, generic industry summaries are insufficient for high-stakes planning. PW Consulting's Worldwide Pharmaceutical Dyes Market research is designed to provide the depth and specificity required for confident decision-making. The report offers a granular examination of segmentation structures, enabling readers to assess the relative attractiveness of different material types and application areas without relying on broad averages. It provides detailed regional analysis that accounts for local regulatory nuances, manufacturing capabilities, and demand drivers, allowing for more precise geographic strategy formulation.
Competitive profiling extends beyond basic company descriptions to include an analysis of strategic moves, product portfolios, and positioning tactics. By examining recent developments such as product launches, certification achievements, and capacity investments, the report reveals the operational priorities of key market participants. This intelligence helps clients identify gaps in their own offerings, anticipate competitor responses, and evaluate partnership or acquisition opportunities. Furthermore, the integration of market dynamics data, including raw material cost trends and regulatory updates, ensures that strategic plans are grounded in the realities of the current operating environment.
Stakeholders will find value in the report's focus on actionable insights. Whether the objective is to refine a product development roadmap, optimize procurement strategies, enter new geographic markets, or assess investment potential, the research provides a structured framework for evaluating options. The combination of historical data, forecast projections, and qualitative analysis creates a holistic view that supports both short-term tactical adjustments and long-term strategic positioning.
Conclusion
The pharmaceutical dyes market is poised for sustained growth, underpinned by the enduring need for effective, compliant, and patient-friendly drug formulations. The projected expansion from 2026 through 2032 offers significant opportunities for companies that can navigate the interplay of material innovation, application-specific requirements, regional differences, and regulatory demands. Success will depend on strategic agility, technical excellence, and a deep understanding of the forces shaping the competitive landscape.
PW Consulting's comprehensive analysis equips industry leaders with the intelligence necessary to anticipate change and capitalize on emerging trends. To access the full dataset, detailed segmentation breakdowns, and complete competitive profiles that underpin this overview, professional stakeholders are encouraged to consult the complete report. This document represents a vital investment in informed strategy, ensuring that your organization is prepared to thrive in a market where color, compliance, and innovation converge.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
2 Dimensional Rotary Tables Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-17
2 Dimensional Rotary Tables Market
Overview
The 2 Dimensional Rotary Tables Market encompasses precision rotary devices used to position and rotate workpieces along two axes, typically for machining, assembly, or inspection processes. These tables are fundamental in manufacturing environments that demand high accuracy and repeatability, supporting industries such as aerospace, automotive, and electronics. By enabling precise multi-axis movement, they enhance productivity, reduce setup times, and improve process quality.
The core functionalities of these rotary tables include smooth multi-directional rotation, load capacity management, and integration with CNC systems. The market for 2 Dimensional Rotary Tables is critical in supporting modern industries that rely on automation and precision engineering. The 2 Dimensional Rotary Tables Market is vital for advancing manufacturing capabilities and enabling complex component fabrication.
Market Size and Growth
The current estimated market value for the 2 Dimensional Rotary Tables Market is approximately USD 1.2 billion. Over the next decade, this market is projected to reach around USD 2.4 billion, reflecting a compound annual growth rate (CAGR) of about 8%. Growth is driven by increasing automation in manufacturing and the rising demand for high-precision machining solutions globally.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2902
Key Drivers
• Growing adoption of automation in manufacturing processes
• Rising demand for high-precision component fabrication
• Technological advancements in rotary table design
• Expansion of industries such as aerospace and electronics
• Increased integration with CNC and robotic systems
Restraints
• High initial investment costs
• Technical complexity in integration and operation
• Regulatory compliance challenges in certain regions
• Operational limitations for extremely heavy loads
• Rapid technological obsolescence
Segmentation
• By Type: Horizontal, Vertical
• By Deployment: CNC-integrated, Manual, Semi-automatic
• By Enterprise Size: Small, Medium, Large
• By End User: Automotive, Aerospace, Electronics, Medical Devices, General Manufacturing
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by advanced manufacturing sectors and automation adoption. Europe’s focus on precision engineering and automotive manufacturing sustains steady growth. In Asia-Pacific, rapid industrialization and expanding electronics industries fuel demand, making it the largest regional market. Latin America shows emerging opportunities, especially in automotive and aerospace sectors. The Middle East & Africa are gradually adopting rotary table technology, mainly in oil & gas and heavy machinery industries.
Opportunities
• Expansion in high-growth regions such as Asia-Pacific and Latin America
• Adoption of smart, IoT-enabled rotary tables for Industry 4.0 initiatives
• Development of lightweight, high-load capacity models
• Integration with robotic and automated assembly lines
• Increasing use in additive manufacturing and 3D printing applications
Key Companies
SMC Corporation, THK Co., Ltd., FIBRO GmbH, Kitagawa, TEMPTRONIC, Schunk, Bosch Rexroth, P. G. Engineering, ISEL, Marposs, Ewag, and Koma Precision, Inc.
Conclusion
The overall outlook for the 2 Dimensional Rotary Tables Market remains positive, supported by ongoing industrial automation and technological innovation. Long-term growth potential is significant as industries seek higher precision and efficiency. The strategic importance of this market lies in its ability to enable complex manufacturing processes and support Industry 4.0 initiatives. The 2 Dimensional Rotary Tables Market will continue to evolve, offering new opportunities for industry players and stakeholders.
Related Reports
Medical Smoke Evacuation System Market , Size Share and Analysis | Report 2033
Medical And Breathing Air Dryer Market , Size Share and Analysis | Report 2033
Diesel Driven Air Compressor Market , Size Share and Analysis | Report 2033
Compressor Heat Recovery System Market , Size Share and Analysis | Report 2033
High Pressure Piston Compressor Market , Size Share and Analysis | Report 2033
Industrial Piston Compressor Market , Size Share and Analysis | Report 2033
Compressed Air Filter Housing Market , Size Share and Analysis | Report 2033
Fabricated Coalescing Filter Market , Size Share and Analysis | Report 2033
Silicone Free Filter Market , Size Share and Analysis | Report 2033
Non Cycling Refrigeration Dryer Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher